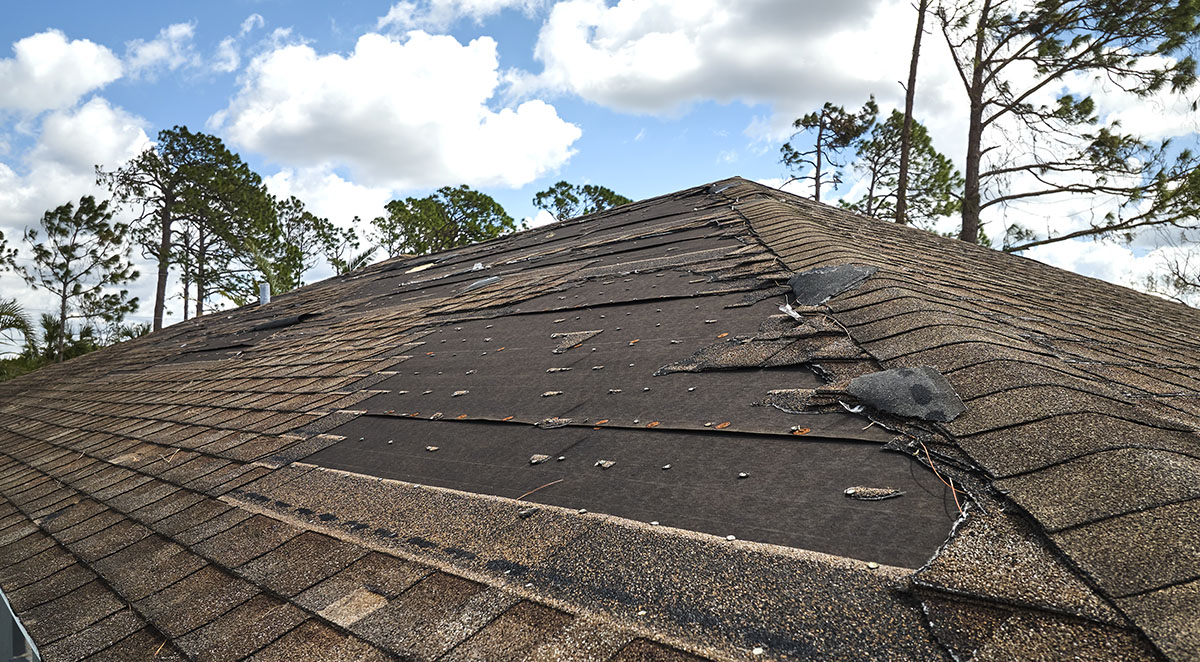
A storm rolls through, and the next morning you notice shingles in the yard or a fresh water stain on the ceiling. You pay your premiums every month, so you expect your insurance company to step in. Then the letter arrives: your claim has been denied.
If that has happened to you, it does not always mean your roof was not damaged. Many insurance claims denied for roof damage come down to avoidable mistakes in how the claim was reported, documented, or presented. At Northwest Roofing, helping homeowners through the claims process is our specialty, and we have seen firsthand how the right approach changes the outcome.
Quick Summary
- Most denied roof claims stem from process mistakes, not a lack of real damage.
- Waiting too long, poor documentation, and meeting the adjuster alone are the most common roof insurance claim mistakes.
- Storm damage is often mistaken for ordinary wear and tear, by homeowners and adjusters alike.
- A professional inspection before you file gives your claim a stronger foundation.
- Northwest Roofing documents damage, meets with your adjuster, and works on your behalf so your carrier meets its obligations.
Why Roofing Claims Fail More Often Than They Should
Adjusters review claims against the specific language in your policy. If the evidence is thin, the timeline is unclear, or the damage looks age related, the claim can be reduced or denied.
The gap between doing it alone and having an expert in your corner is significant. Less than 10% of roof claims are completely covered when homeowners deal with the insurance company on their own. When Northwest Roofing handles the claim, over 70% of roofs are covered by insurance.
Your local agent may be wonderful, but your agent does not decide whether your carrier properly covers storm damage. That decision rests with the carrier and its adjuster. Understanding why roofing claims fail is the first step toward making sure yours does not.
The Most Common Roof Insurance Claim Mistakes
Each of the mistakes below is avoidable with the right knowledge and support.
1. Waiting Too Long to File
Most homeowners policies set time limits for reporting damage, and those limits vary from policy to policy. Waiting weeks or months after a storm can give the insurer grounds to question whether the damage came from that event at all.
Delays also allow small problems to grow. A minor leak left alone can affect decking, insulation, and ceilings, and an insurer may argue that the additional damage resulted from neglect rather than the storm. If you suspect damage, schedule an inspection promptly and review your policy for its reporting requirements.
2. Not Recognizing Storm Damage
Most homeowners do not even know what storm damage looks like. Hail bruising, lifted shingle tabs, and granule loss are easy to miss from the ground, yet they can shorten the life of your roof by many years.
When damage goes unnoticed, homeowners often file late or never file at all. Others report only one obvious leak and miss widespread damage elsewhere. Our guide on what to do after storm damage to your roof walks through the warning signs.
3. Weak or Missing Documentation
Adjusters rely on evidence. A claim with a few blurry phone photos taken from the driveway rarely holds up as well as one supported by clear, close-up images and video of each damaged area.
Strong documentation typically includes:
- Dated photos and videos of the roof surface, flashing, vents, and gutters
- Images of interior damage such as ceiling stains or wet insulation
- Notes on the date and type of storm that caused the damage
- Records of every conversation with your insurance company
4. Letting Storm Damage Be Labeled as Wear and Tear
Standard homeowners policies generally cover sudden, accidental damage from events like wind and hail, while excluding gradual deterioration. That distinction is where many claims are won or lost.
An older roof can still suffer genuine storm damage, but if the evidence does not clearly separate new damage from normal aging, the adjuster may attribute everything to wear and tear. Knowing the difference, and being able to show it, is essential. Learn more in our article on what kind of roof damage is covered by insurance.
5. Making Permanent Repairs Before the Adjuster Visits
Replacing shingles or having a full repair done before the adjuster inspects the roof can remove the very evidence your claim depends on.
Many policies do expect homeowners to take reasonable steps to prevent further damage, so temporary measures to stop active leaks may be appropriate. The key is to document everything first and check with your insurer before any permanent work begins.
6. Meeting the Adjuster Alone
This is one of the most costly roof insurance claim mistakes. After a major storm, adjusters often inspect many roofs in a short time. Without a roofing professional present, damage can be overlooked, misidentified, or left out of the estimate entirely.
Having an experienced roofer alongside the adjuster means someone is pointing out every damaged area and making sure nothing is missed.
7. Accepting the First Answer Without Question
A denial or a low settlement is not always the final word. Homeowners frequently accept the first decision because they assume it cannot be challenged or they do not know what to look for in the paperwork.
Comparing the adjuster's findings to an independent professional inspection can reveal gaps worth raising with your carrier.
How Northwest Roofing Advocates for You
Since 1999, our roofing division has helped families and businesses across Western North Carolina with dependable roofing services. Insurance claims are where our advocacy matters most. We know how insurance works, and we work on your behalf to make sure that if you do have roof damage, your insurance carrier meets its obligations and responsibilities.
Here is how the process works when you call us:
- A Northwest Roofing representative inspects your roof and documents the damage with photos and videos.
- You contact your insurance provider to initiate the claim.
- A Northwest Roofing representative meets with your insurance adjuster to assess the damage together.
- Northwest Roofing, the adjuster, and you work together to finish the paperwork and complete the necessary repairs.
Keep records of each step and stay in touch with both your insurer and our team. If we find wind or hail damage, we will help you through the claims process. As a matter of fact, the hardest thing you will need to do is pick out a color.
We are a licensed NC General Contractor through our parent company (license 86294) and a Better Business Bureau A+ Rated and Accredited Business. For a deeper look at the process, read our guide on how to get insurance to pay for a roof replacement.
What to Do If Your Claim Was Already Denied
A denial is worth a closer look before you give up. Consider these steps:
- Ask your insurance company for the reason for denial in writing.
- Review your policy language on covered perils and exclusions.
- Gather all photos, videos, and records related to the damage and the storm.
- Schedule an independent professional roof inspection to see whether storm damage was missed.
- Contact your insurer to ask about its process for reconsideration or reinspection.
Our free, no-pressure inspection can help you understand whether your roof shows signs of storm damage that deserve a second look. You can also visit our leaks and storm damage page to learn more about how we help.
Frequently Asked Questions
Why do roof insurance claims get denied?
The most common reasons include late reporting, insufficient documentation, damage being classified as wear and tear, and repairs made before the adjuster inspected the roof. Many denials result from how the claim was handled rather than the absence of real damage.
Should I call my roofer or my insurance company first?
Scheduling a professional inspection first helps you understand whether you have storm damage and how extensive it is. That way, when you contact your insurer, you have documentation ready to support your claim.
Can an older roof still qualify for an insurance claim?
Yes, an older roof can still sustain covered storm damage. The challenge is clearly showing which damage came from the storm and which came from normal aging, which is why expert documentation matters.
Will Northwest Roofing meet with my insurance adjuster?
Yes. A Northwest Roofing representative meets with your adjuster to assess the damage, point out problem areas, and help make sure the full scope of storm damage is considered.
Does Northwest Roofing charge for roof inspections?
No. We offer free roof inspections for both residential and commercial customers.
Protect Your Claim by Getting the Right Help
Insurance claims get denied for many reasons, but most are preventable. Acting quickly, documenting thoroughly, and having an experienced roofing professional advocate for you can make the difference between a denied claim and a covered roof.
You do not have to face your insurance company alone. Whether you have a shingle roof, a metal roof, or a commercial flat roof, our team is ready to help. Contact Northwest Roofing today or call 844-766-3762 to schedule your free roof inspection.